The future of the circular economy: Carina Stöttner speaks at IFAT for the steel and metal recycling industry
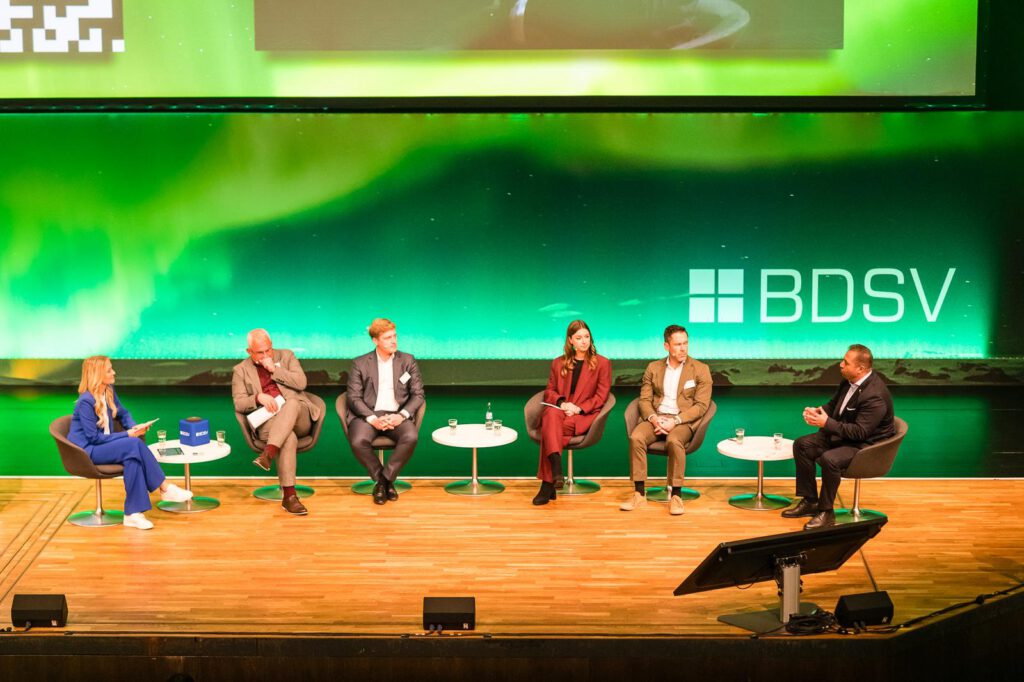
Munich, IFAT 2026 — the world’s leading trade fair for environmental technology. Four people share a stage to work through a question that could hardly matter more to Europe’s industrial future: where is the circular economy heading — toward a high-tech, globally integrated system? Or will protectionism and geopolitical fragmentation pull it back from the international stage?
The session was hosted by BDSV, the German association of steel recycling and waste management companies, and VDM, the German association of metal traders and recyclers — two bodies currently merging into the future Circular Metal Association. On the panel: Murat Bayram, Andreas Schwenter, Prof. Frank Pothen — and futurist Carina Stöttner, whose short keynote set the frame for the discussion.
What emerged reaches well beyond the sector itself: steel and metal recycling is one of the places where it will be decided whether Europe stays industrially sovereign — and whether it does so in a way that holds up over time.
The underestimated industry: what already exists
Before talking about the future, it’s worth looking at the present. In Germany alone, roughly 10,000 circular economy companies account for some 300,000 jobs. Across Europe, the figure runs into several million. Family-run mid-sized firms, specialist plant builders, highly automated sorting operations — over the past decades they have invested billions in shredding plants, modern processing technology and AI-assisted sorting.
Murat Bayram’s message on the panel was accordingly blunt: this industry needs to stop talking itself down. Recycling operations aren’t a burden on the environment — they are, in Andreas Schwenter’s words, environmental protection facilities. They secure raw materials, avoid CO₂, make green steel possible and lay the foundation for industrial value creation in Europe.
Prof. Frank Pothen supplied the economic backing: every ton of recycled steel scrap avoids substantial CO₂ emissions. The circular economy isn’t a footnote to climate policy — it’s the practical core of it.
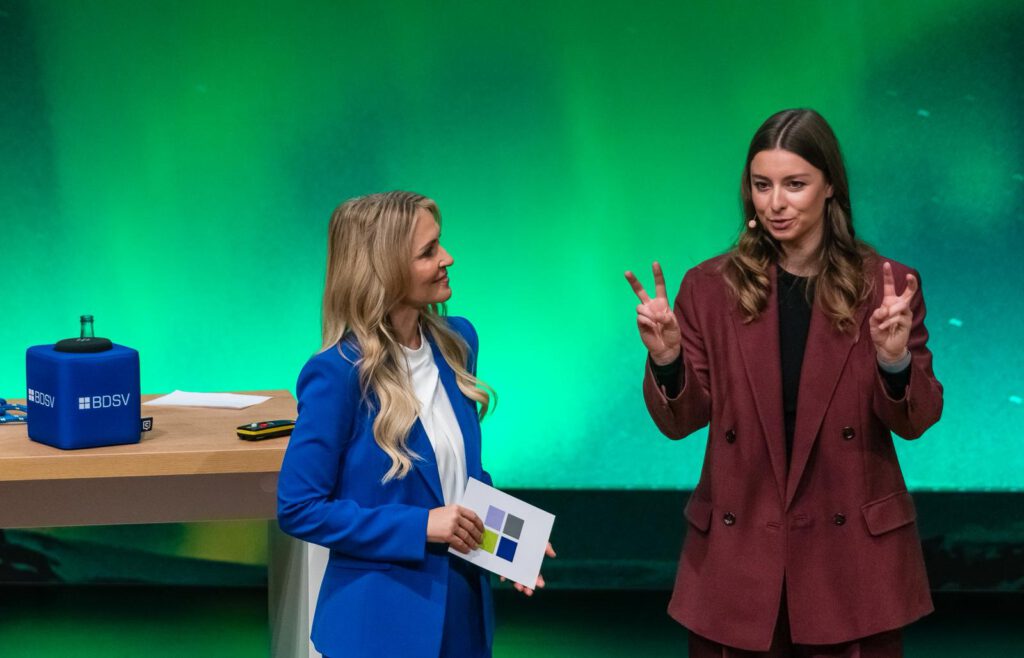
It was into this picture that Carina Stöttner delivered her talk — and opened up the view forward.
Stöttner’s scenarios: possible futures for the circular economy
Her opening question was deliberately pointed: where is our industrial economy heading? And what does that mean for the steel, metal and recycling sector?
- Scenario A — the high-tech circular economy. A globally integrated circular economy in which AI sorting, robotics, new materials science, digital material passports and international cooperation reinforce one another. Recycling rates climb sharply, secondary raw materials reach primary-grade quality, and Europe becomes the technology leader in a growth market.
- Scenario B — the customers leave. Production shifts largely overseas, and with it goes both the raw material in the form of production scrap and the demand for recycled material.
- Scenario C — the fragmented protectionist economy. Rising protectionism, new export bans, regional walls. The industry loses economies of scale, investment capacity and the pressure to innovate. The circular economy remains necessary, but never becomes a global growth market.
Her point: which scenario arrives isn’t a forecast. It’s a decision. And that decision is being made right now — in Brussels, in Berlin, in supervisory boards, in investment committees.
Deep tech as the formula for the circular economy’s future
What Stöttner made particularly clear at IFAT: the next stage of the circular economy is a deep tech stage.
In practice, that means:
- AI-assisted sorting and material identification, delivering secondary raw materials at grades only primary materials reach today
- Robotics in the disassembly of complex products — from electric vehicles to wind turbines to electronics
- New materials and processes that build recyclability into product design from the outset
- International cooperation in research, standards and trade, because no single market is large enough to carry these investments alone
The trade-off: when protection weakens the industry it’s meant to protect
This is exactly where Stöttner’s keynote met the associations’ pointed position on the panel. Andreas Schwenter and Murat Bayram were unambiguous on one point: protectionism, export bans and additional trade barriers are not a strategy for the future.
The reasoning isn’t ideological — it’s industrial:
- Close off markets and you drain the industry’s investment capacity. Recycling technology scales with global sales markets, not with domestic leftovers.
- Restrict scrap exports and you slow innovation. International competition is precisely what built the German recycling industry into the leader it is today.
- Bet on self-sufficiency and you lose quality. Secondary raw materials require specialization, material purity and international flows. Closed systems produce lower grades at higher cost.
- Bury mid-sized firms in bureaucracy and you weaken the backbone of the whole system. The ten thousand companies carrying it need conditions that enable rather than obstruct.
None of which argues against sovereignty. It argues for intelligent sovereignty rather than a reflex to build walls. Strategic reserves, diversified flows of critical materials, European standards — yes. Blanket long-term export bans and new barriers — no.
Stöttner’s contribution: an industry that pulls up the drawbridge buys short-term security and loses its long-term future. The circular economy worth aiming for is open, cooperative and technologically ambitious — not defensive.
What the industry needs now: less nostalgia, more nerve
Four imperatives for the years ahead emerged from the panel and Stöttner’s keynote — not as finished answers, but as the right questions:
- Confidence, not justification. For decades this industry has been solving in practice what others demand in theory. That record belongs in the public story about climate protection and industrial sovereignty.
- Deep tech investment now. AI, robotics, new materials and digital traceability are past the pilot stage. They are the sector’s base technologies for the next twenty years.
- Conditions that enable. Less bureaucracy, faster permitting, reliable energy and trade policy — so that investment happens in Europe rather than elsewhere.
- International cooperation as strategy. European strength won’t come from going it alone, but from alliances with global partners, shared standards and open markets — while retaining sovereignty in genuinely critical areas.
The announced merger of BDSV and VDM into the Circular Metal Association fits that line exactly: more clout, more common ground, more future — and an industry finally positioning itself the way it has long since been built.
The takeaway: the future of the circular economy can be shaped
Stöttner’s central message at IFAT: the future isn’t written. It can be shaped.
Whether Europe builds a global high-tech circular economy or retreats into a fragmented protectionist one won’t be settled by forecasts. It will be settled in the next rounds of investment, in the next wave of European regulation, in whether the industry takes its own strength seriously — and whether policymakers have the nerve to open up room for possibility rather than close it down.
About the event
IFAT Munich is the world’s leading trade fair for water, wastewater, waste and raw materials management. The joint stage session hosted by BDSV and VDM — the German steel and metal recycling associations now merging into the Circular Metal Association — brought together:
- Carina Stöttner, futurist and CEO, Futurewise Company
- Murat Bayram, President, VDM
- Andreas Schwenter, President, BDSV
- Prof. Frank Pothen, Professor of Economics, Ernst-Abbe-Hochschule Jena